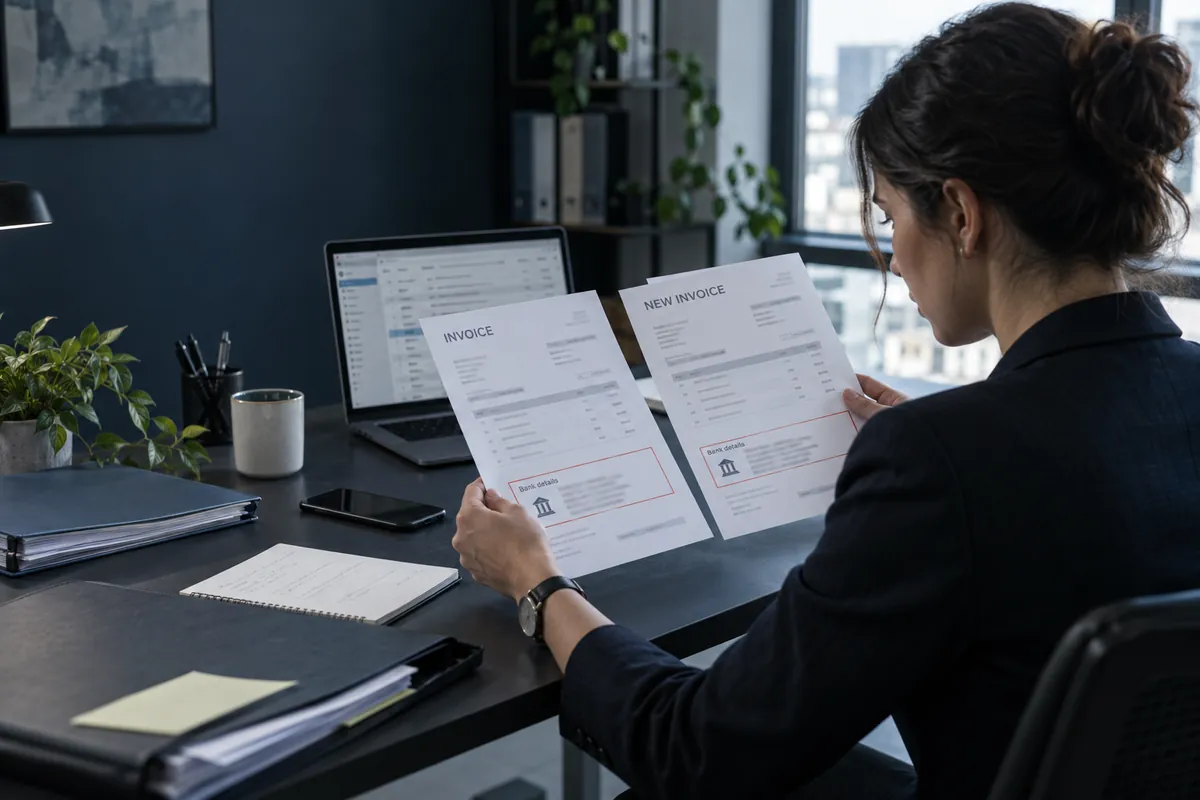
Verify changed supplier bank details before paying.
A genuine invoice can arrive with a forged email, and an old conversation can be hijacked. Verify the change request, the channel and the beneficiary independently instead of relying on the document alone.
Pause payment to the new account while the change is checked.
Call the supplier using a contact known before the request.
Require a second approver under the organisation's payment process.
Keep messages and approval records without circulating bank details unnecessarily.
Step-by-step method
A reproducible path from question to conclusion.
1
Freeze the change
Do not replace the account in the payment system or release the requested transfer. Record the due date, amount and people who received the request so that a parallel payment does not slip through.
2
Preserve the message and invoice
Keep the original email with its headers, the invoice and earlier exchanges. Record the actual sending address and any change of domain or tone, without treating one signal as a verdict.
3
Reach the supplier independently
Use the number already held in the supplier record or an official channel established before the request. Do not call a number in the email or revised invoice. Confirm the authorised contact and stated effective date.
4
Apply dual control
Have someone other than the person entering the change compare the confirmation, previous details, beneficiary and supporting document. Record what was checked, by whom and when.
5
Decide and monitor
If confirmation remains unavailable or contradictory, keep the change on hold and escalate to the finance owner. Once approved, monitor the first payment and retain the authorisation with the supplier record.
A familiar conversation may contain a fraudulent message
An old email thread or an invoice carrying the correct logo does not prove the new instruction came from the supplier. A compromised mailbox can reply within a legitimate conversation; an intercepted invoice can be altered while its other lines stay intact.
Compare the domain, beneficiary name, account history and commercial context. These clues guide the review, but a separate known channel must establish the change.
Treat a bank-detail change as a controlled event
The task is wider than spotting a suspicious email. A maintained supplier record, a second approval and separation between data entry and payment prevent a single instruction from redirecting funds.
An urgent closing date or conditional discount does not remove this control. Agree an escalation route in advance for times when the usual supplier contact cannot be reached.
Interpret the bank’s payee check
For standard and instant SEPA transfers in France, the name entered is checked against the holder of the IBAN. UK Confirmation of Payee offers an account-name check for domestic payments. Ask your bank which checks are available for cross-border transfers.
If the result is a close match, a mismatch or unavailable, hold the transfer. Contact the supplier’s authorised representative through an established channel to confirm the registered name and account details. Record the result and send any corrected details to the second approver.
A match checks the link between the account and the name within the service’s scope. Confirm separately that the supplier authorised the change and that the invoice matches the intended payment.
If a transfer has already been sent
Contact the bank immediately through its official channel and ask about recall or blocking options. Alert the finance owners and internal response team; do not assume a recall can succeed.
Preserve the transfer order, references, original messages and approval timeline. Work with the relevant professionals to assess reporting and other payments that may use the changed details.
Separate supplier records from payment
Invoice approval and beneficiary-account change are separate decisions. Identify receipt, verification and approval responsibilities. Retain earlier supplier records and callback results. New contact details supplied with a change cannot independently confirm themselves.
Prepare an accurate payment timeline
Record request, approval and order times, amount and reference for the bank. Separate entered order, executed transaction and recovery attempt; do not promise cancellation. A supplier denial establishes a contradiction, not automatically the fraudster’s identity or method.
Reading technical evidence
Read Authentication-Results within its trust context
A result copied into an email is not automatically trustworthy. Its origin in the mail chain matters.
Field or situation and its interpretation
Observed item
What it means
authserv-id
Identify the service claiming to have performed the check.
spf=pass or dkim=pass
Read the mechanism and domain concerned, rather than just the word pass.
An upstream header
Ask the mail team which results originate from its trusted services.
Preserve the original message and headers. Even a trustworthy result does not authorise a requested bank-account change.
The verification channel must be independent of the message
A familiar signature, attached invoice or existing email thread does not authenticate new bank details. Pause the supplier-record change and call a previously verified number. Retain who confirmed the request, when and through which channel.
Agree who receives the request, who makes the callback and who approves the change. Separate entry from approval where possible. If a transfer has already been ordered, contact the bank immediately with the times, amount and payment references, and preserve the original message and bank-details document. Do not wait for the suspicious sender’s reply.
Receipt
Pause the requested change before updating records.
Callback
Use a previously verified supplier contact.
Response
Contact the bank immediately if payment was ordered.
Is replying in the supplier’s thread sufficient?
No. A thread can be compromised or imitated. Confirm through a channel whose details were held before the suspicious request.
Try the reasoning
The new-bank-details message also supplies a callback number. Is that independent?
Reasoning: No. Use a contact already verified in the supplier’s established records.
Fictional teaching case, not a client investigation.
Did the known supplier authorise the request? The company’s existence and authorisation of the change are separate questions.
Observation, interpretation and limit
Observation
What it establishes
What remains unproven
A message quotes the correct invoice number and supplies new bank details.
The message knows about the transaction.
Details can come from compromised correspondence; they do not identify the sender.
A public register confirms that the named company exists.
An entity exists under that identifier.
The register does not confirm the message, bank account or sender’s authority.
The usual contact, called using a number retained before the message arrived, does not confirm the change.
The request is unconfirmed through the independent channel used.
Fraud, error and a poorly coordinated internal process remain possible explanations.
Conclusion to record
Company identified; payment change unconfirmed. Do not treat the message as authorisation to update the supplier record. Refer the discrepancy to the payment owner and request confirmation through the usual procedure.
What would change the conclusion?
Review after documented confirmation by an authorised contact through previously held contact details. Keep the response and record who authorised the change.
Check your reasoning
Calling a number in the suspicious message removes the check’s independence. A correct invoice and a real company do not repair that weakness.
For each point, record what the material actually supports. “Supported” applies to the specific observation, not to the entire case. A contradiction needs explanation; missing material remains an open question.
Define the question
Record the source
Test the observation
State the limits
Entries stay in this page until you leave or reload it. Nothing is saved or submitted by this tool. Use neutral references instead of personal data or credentials.
How to write a useful conclusion
Editorial examples, not findings about your case
Material
Useful wording
Next check
One dated source
The consulted source stated X on the recorded date.
Check its origin and whether it still applies.
Multiple copies of one claim
Several pages repeat X; independent corroboration is missing.
Find the original and a source with independent evidence.
Conflicting sources
A states X while B states Y; the difference is unresolved.
Compare dates, scope, identifiers and definitions.
No matching result
No result was found in the recorded scope.
Describe queries, coverage and access limitations.
What to check and what to record
Use this grid to turn the method into a reviewable case file. A missing item remains an open question. The interpretation limit prevents a finding from becoming an unsupported conclusion.
Topic-specific checks
Check
Useful record
Interpretation limit
Change
Old and new details, date and original request.
A technically valid IBAN does not confirm the beneficiary.
Independent callback
Previously known contact, person reached and recorded outcome.
Do not call a number added to the suspicious request.
Dual control
Two separate approvals before amendment and payment.
A small test transfer does not establish recipient identity.
Common pitfalls
Four shortcuts that weaken the result.
Calling the supplied number
A number inserted into the request may connect directly to the fraudster.
Trusting the email thread
A compromised mailbox can write within a genuine conversation.
Approving alone
One person should not enter, confirm and release a sensitive payment.
Deleting the request
Original messages and timing help the bank and response team understand the case.
Practical questions
Frequently asked questions.
Is a company name beside the account enough?
No. The displayed name may be incomplete or unverified depending on the channel. Confirm the change with the supplier independently and follow the applicable bank process.
What if the supplier cannot be reached?
Keep payment to the new account on hold and escalate to the responsible owner. A commercial deadline does not justify bypassing the check.
Does a signed email or official-looking PDF prove the change?
No. Either may be copied or sent from a compromised account. Its value rises when paired with independent confirmation and a recorded approval chain.
What if the bank shows a close match?
Keep the transfer on hold. Ask the supplier to confirm its name and bank details through a known contact, then ask the second approver to verify the change.
Public references
These primary references support the checks described here. The sequence and working sheet are an IIS editorial method; a cited organisation does not endorse this guide. Read each reference within its stated date, jurisdiction and scope.
Published by Internet Intelligence Service on 26 September 2026. Last content update: 15 November 2026. This educational guide describes a lawful, defensive method. It is not legal advice, an emergency service or authority instruction.